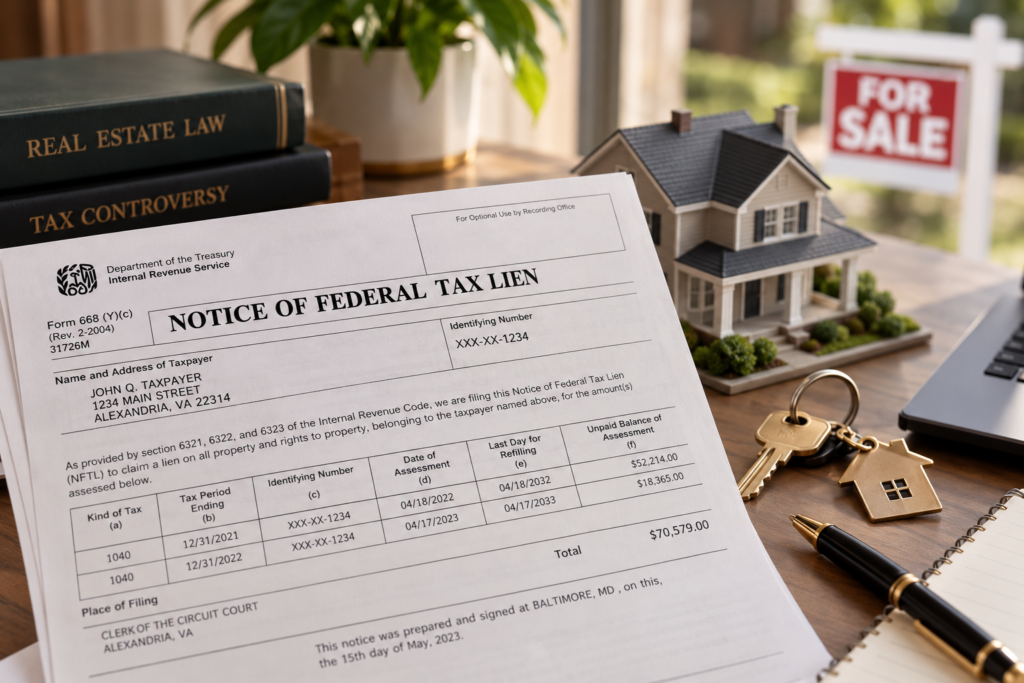
Discovering a federal tax lien against your home can make an already difficult tax situation feel even more complicated—especially if you are planning to sell, refinance, or borrow against the property.
A federal tax lien, however, does not necessarily mean that a real estate transaction cannot move forward.
Depending on your circumstances, there may be IRS procedures that allow you to sell your home, obtain financing, address the public lien filing, or coordinate the transaction with a broader resolution of your tax debt.
Understanding which option applies—and addressing it early—can be important when a closing date, financing deadline, or IRS deadline is approaching.
What Is a Federal Tax Lien?
A federal tax lien is the government’s legal claim against your property for unpaid federal tax.
The Notice of Federal Tax Lien, commonly called an NFTL, is the public filing that alerts other creditors to the government’s claim. That filing may surface during title or lending reviews and can affect your ability to sell or borrow against your home.
A federal tax lien is also different from an IRS levy. A lien is a legal claim against property, while a levy is an action used to take property or money to collect a tax debt.
Understanding that distinction is an important first step when considering your options.
Can You Sell a Home With a Federal Tax Lien?
Potentially.
One option that may allow a transaction to proceed is a certificate of discharge.
A discharge removes the federal tax lien from the specific property described in the certificate. This may allow a buyer to receive the property free of that federal lien even though the homeowner continues to owe taxes.
Importantly, a discharge generally does not eliminate the underlying tax debt or remove the lien from other property.
The IRS evaluates its interest in the property after considering factors such as the property’s value, claims with higher priority, and acceptable sale expenses.
For example, a home could sell for $500,000 while a senior mortgage requires a $420,000 payoff and approved sale expenses total $30,000. In that simplified example, $50,000 may remain available for the IRS lien interest.
If the homeowner owes $120,000 and the IRS approves a $50,000 discharge payment, the sale may be able to proceed while approximately $70,000 of the tax debt remains unresolved, before additional interest, penalties, or adjustments.
A discharge may also be possible in some circumstances where there is no equity available for the IRS, but the IRS will require documentation supporting the property’s value and the claims with higher priority.
What If You Want to Keep the Home and Refinance?
Selling is not the only situation in which a federal tax lien can become an issue.
If you want to refinance your mortgage or obtain a second mortgage, subordination may be an option to evaluate.
Subordination does not remove the federal tax lien. Instead, it allows a specified lender to move ahead of the IRS in priority when the legal requirements are satisfied.
For example, new financing might provide funds that are paid to the IRS. In another situation, refinancing might reduce a homeowner’s monthly mortgage obligation and improve the amount the IRS can ultimately collect.
The IRS evaluates the particular transaction and supporting financial information.
Even when the IRS approves subordination, the lender must independently approve the loan. IRS approval also does not mean that taking on new debt is financially appropriate for the homeowner.
Release and Withdrawal Are Different
Two other terms homeowners may encounter are release and withdrawal.
A release extinguishes the federal lien covered by the certificate after the applicable legal requirements have been satisfied, such as payment in full or completion of the payment terms of an accepted offer in compromise.
Withdrawal addresses the public Notice of Federal Tax Lien in qualifying circumstances. Withdrawal of the NFTL does not itself forgive the underlying tax debt.
Because discharge, subordination, release, and withdrawal accomplish different things, the appropriate procedure depends on both the property transaction and the taxpayer’s broader situation.
Coordinating a Property Transaction With an Offer in Compromise
Some homeowners may also be considering an offer in compromise, which asks the IRS to settle specified tax liabilities for less than the full amount owed.
When a property sale or financing is also involved, timing can become particularly important.
Proceeds from an approved sale or financing may, in qualifying circumstances, count toward an accepted offer through coordinated IRS processing. However, approval of a discharge or subordination request does not mean the IRS has approved the offer in compromise.
If discharge or subordination proceeds are paid before the offer is submitted, those amounts generally cannot later be reused as an offer payment.
The IRS also considers more than the proceeds from the home. For a collectibility-based offer, the IRS evaluates assets, income, allowable expenses, and other relevant circumstances.
This is why the sequence of a property transaction and a tax-resolution strategy should be considered before funds are distributed.
What Happens If a Federal Tax Lien Is Left Unresolved?
Ignoring an NFTL can create complications later.
The filing may appear during a future title or lending review and could delay a sale, interfere with financing, or affect how proceeds must be distributed.
Interest and applicable penalties may also continue to increase the outstanding tax balance. Subject to applicable notice requirements and protections, the IRS may pursue additional collection activity.
Homeowners should also pay careful attention to deadlines. A pending discharge or subordination application does not automatically stop IRS collection activity or preserve an appeal deadline.
Likewise, the collection period should not be calculated simply from the date an NFTL was recorded. The applicable period generally runs from assessment, and certain events—including bankruptcy, offers in compromise, and some appeals—can affect the calculation.
Start Before the Closing Date
Waiting until the final days before closing can significantly complicate a transaction.
IRS Publications 783 and 784 call for submission at least 45 days before the transaction date when the applicable certificate is needed. Preparation should begin before that point, and approval or completion may take longer.
If you are considering a sale or refinance, useful documents may include:
- The Notice of Federal Tax Lien and recent IRS correspondence
- Existing payment or offer agreements
- The property deed
- Mortgage payoff information
- Estimated property value
- Proposed sale or loan terms
- Preliminary closing information
- Any collection, levy, foreclosure, or court notices
If there is already a closing date, foreclosure notice, levy notice, or IRS appeal deadline, identify that date immediately.
Evaluating the Property and Tax Debt Together
A federal tax lien does not automatically eliminate your ability to sell or finance your home.
The appropriate strategy may involve a discharge, subordination, release, withdrawal, payment arrangement, offer in compromise, or another tax-resolution option depending on the circumstances.
Basis Law represents taxpayers in federal tax controversy matters. We can review the IRS notices, proposed property transaction, and broader tax situation to evaluate which options may be appropriate and how the transaction should be coordinated with the remaining tax debt.
Need help evaluating a federal tax lien affecting your home? Contact Basis Law to request a federal tax lien consultation.
This article provides general educational information and does not constitute legal advice or create an attorney-client relationship. Results are not guaranteed, and representation requires a written engagement agreement.
Informational notice: This resource is provided for general informational purposes only and is not legal or tax advice. Reading this article, contacting Basis Law PLLC, or submitting information does not create an attorney-client relationship. Legal outcomes and procedural options depend on the specific facts and applicable law.