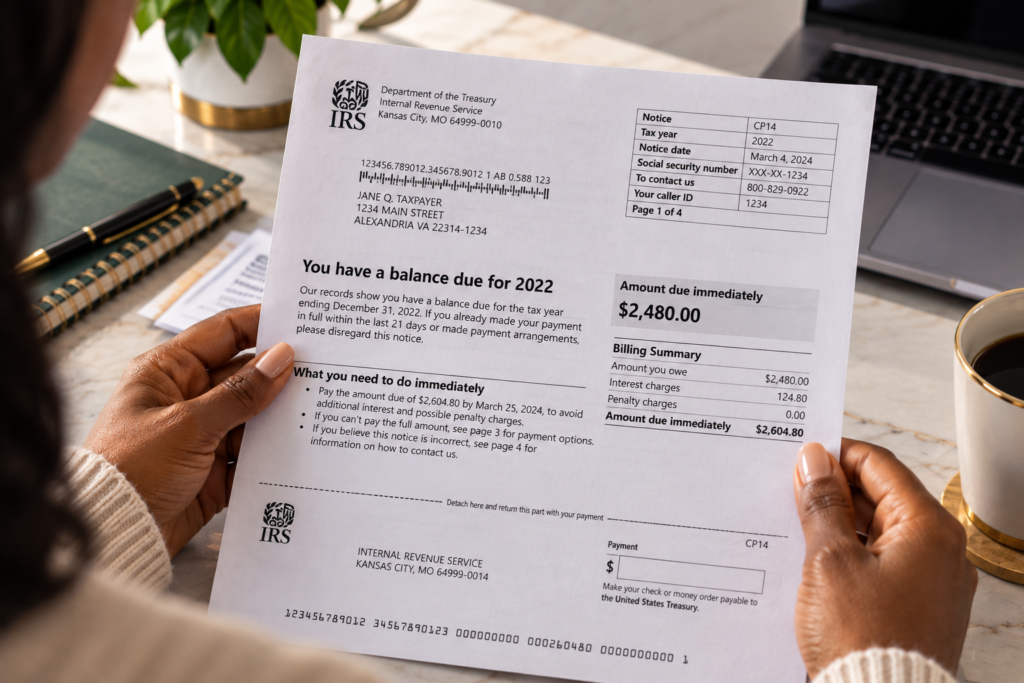
Receiving a letter from the IRS can be unsettling. The envelope may contain unfamiliar terminology, an amount the IRS says is due, or a deadline that appears to require immediate action.
But an IRS notice does not necessarily mean the IRS is correct, and it does not mean every notice should be handled in the same way.
Before paying the amount shown, calling the IRS, or sending a written response, it is important to understand exactly what the notice concerns. A useful starting point is to check three things: the tax period, the response date, and the issue the IRS has identified.
1. Confirm the Tax Period
Start with a basic question:
Which tax year or tax period is the IRS contacting you about?
IRS correspondence generally identifies the tax period involved. That information matters because taxpayers may have multiple returns, amended returns, payments, extensions, or prior communications with the IRS.
Before responding, compare the notice with your records for the identified period. Depending on the issue, useful documents may include:
- The tax return that was filed
- An amended return, if applicable
- IRS account transcripts
- W-2s, 1099s, K-1s, or other tax documents
- Proof of estimated or other tax payments
- Previous IRS correspondence
- Documents supporting deductions, credits, or other reported items
Do not assume that a notice relates to your most recently filed return.
Why the Tax Period Matters
Suppose a taxpayer receives a notice in 2026. The notice may concern a 2024 return rather than the taxpayer’s 2025 return.
Responding based on records from the wrong year can create unnecessary confusion and may fail to address the issue the IRS is actually raising.
Identifying the correct tax period gives you a starting point for reconstructing what happened.
2. Identify the Response Date
Next, look carefully for any date by which the IRS says you should respond or take action.
Not every date appearing on an IRS notice has the same legal significance. Depending on the type of correspondence, a deadline may relate to providing information, disputing a proposed adjustment, requesting administrative review, responding to collection activity, or exercising other procedural rights.
Some tax deadlines can have significant consequences.
For example, certain IRS deficiency procedures can result in a Notice of Deficiency that gives the taxpayer a limited period to petition the United States Tax Court. Other collection notices may involve separate rights and deadlines.
The specific rules depend on the notice and circumstances.
Do Not Rely Only on the Date You Opened the Letter
A common mistake is calculating time based on when the taxpayer happened to read the notice.
Instead, review the notice itself. Look at:
- The notice date
- The response or payment date
- Any separately stated appeal or petition deadline
- Instructions explaining how and where to respond
If you are uncertain about the significance of a deadline, consider obtaining professional advice promptly rather than assuming additional time will be available.
3. Understand What the IRS Says Is Wrong
Once you know the tax period and relevant dates, determine why the IRS sent the notice.
Do not focus only on the balance printed at the top of the page.
Read the explanation.
The IRS may be contacting a taxpayer for many different reasons. For example, correspondence might concern reported income, a mathematical adjustment, missing information, a payment issue, penalties or interest, a proposed change following an examination, or collection of an existing liability.
The appropriate response depends heavily on the underlying issue.
Compare the IRS Position With Your Records
If the IRS says information reported by a third party does not match the tax return, determine what information is different.
If a payment appears to be missing, review records showing when and how the payment was made.
If the IRS changed a deduction or credit, determine what documentation supports the position taken on the return.
If the notice follows an examination, identify exactly which proposed adjustments remain disputed.
The goal at this stage is not necessarily to prepare an immediate response. It is to understand the difference between what was reported and what the IRS now says should have happened.
Should You Call the IRS Immediately?
Sometimes calling the IRS can help clarify an account issue. In other situations, particularly where the notice involves a substantive dispute or important procedural rights, it may be useful to understand the matter before making contact.
Before calling, have the notice and relevant records available.
If the issue is complex, involves a significant amount, follows an audit, concerns collection activity, or could affect appeal or Tax Court rights, consider whether professional guidance would be appropriate before responding.
Should You Pay the Amount on the Notice?
An IRS notice showing an amount due should be taken seriously, but receiving a notice does not by itself answer whether the amount is correct.
First determine:
What created the balance?
Does it match the return and payment history?
Is the IRS proposing a change or stating an assessed balance?
Are there rights or procedures for challenging the issue?
The answers depend on the type of notice and the taxpayer’s circumstances.
Keep the Entire Notice
Do not discard the envelope or pages that appear unimportant.
Keep a complete copy of the correspondence together with any response and supporting documents.
If you communicate with the IRS, maintaining a simple record can also be useful. Note the date, method of communication, what was submitted or discussed, and any follow-up that was requested.
Good records can become particularly important if the issue continues over multiple months or moves into another stage of the administrative process.
A Simple Framework
When an IRS notice arrives, start with three questions:
1. What tax period does this concern?
Make sure you are reviewing the correct return and records.
2. When do I need to act?
Identify every response or procedural deadline stated in the correspondence.
3. What exactly does the IRS say is wrong?
Understand the underlying issue before deciding how to respond.
Those three questions will not resolve every tax controversy, but they can help you understand what you are dealing with and what information may be needed next.
When an IRS Notice Becomes a Tax Controversy
Some IRS correspondence involves relatively straightforward account issues. Other notices can be the beginning—or continuation—of a more substantial federal tax dispute.
A matter may warrant closer attention when it involves an examination, significant proposed liability, penalties, collection activity, administrative appeal rights, or potential U.S. Tax Court proceedings.
The earlier the notice is understood, the easier it is to evaluate the available options before an important deadline passes.
Received an IRS Notice?
Basis Law assists individuals and businesses with federal tax controversy and IRS matters. Federal tax representation may be available to clients nationwide.
If you received IRS correspondence and are unsure what it means or how to respond, you can schedule a consultation to discuss the notice and the circumstances surrounding it.
This article is provided for general informational and educational purposes only and does not constitute legal advice. Reading this article, visiting this website, or contacting Basis Law does not create an attorney-client relationship. Tax matters are fact-specific, and applicable procedures and deadlines depend on the particular circumstances.
Informational notice: This resource is provided for general informational purposes only and is not legal or tax advice. Reading this article, contacting Basis Law PLLC, or submitting information does not create an attorney-client relationship. Legal outcomes and procedural options depend on the specific facts and applicable law.